KARACHI: Almost every discussion of the Pakistan Stock Exchange eventually reaches Oil & Gas Development Company — OGDC. It is among the largest companies on the exchange, a fixture of the KSE-100, and for many investors the default way to own a piece of Pakistan's underground wealth. But what does an exploration and production company actually do all day, and where does its money come from? The model is simpler than the geology: find hydrocarbons, produce them, sell them at regulated but dollar-linked prices, and share the proceeds with the state that owns most of the company and the shareholders who own the rest.
First, what an E&P company is — and is not
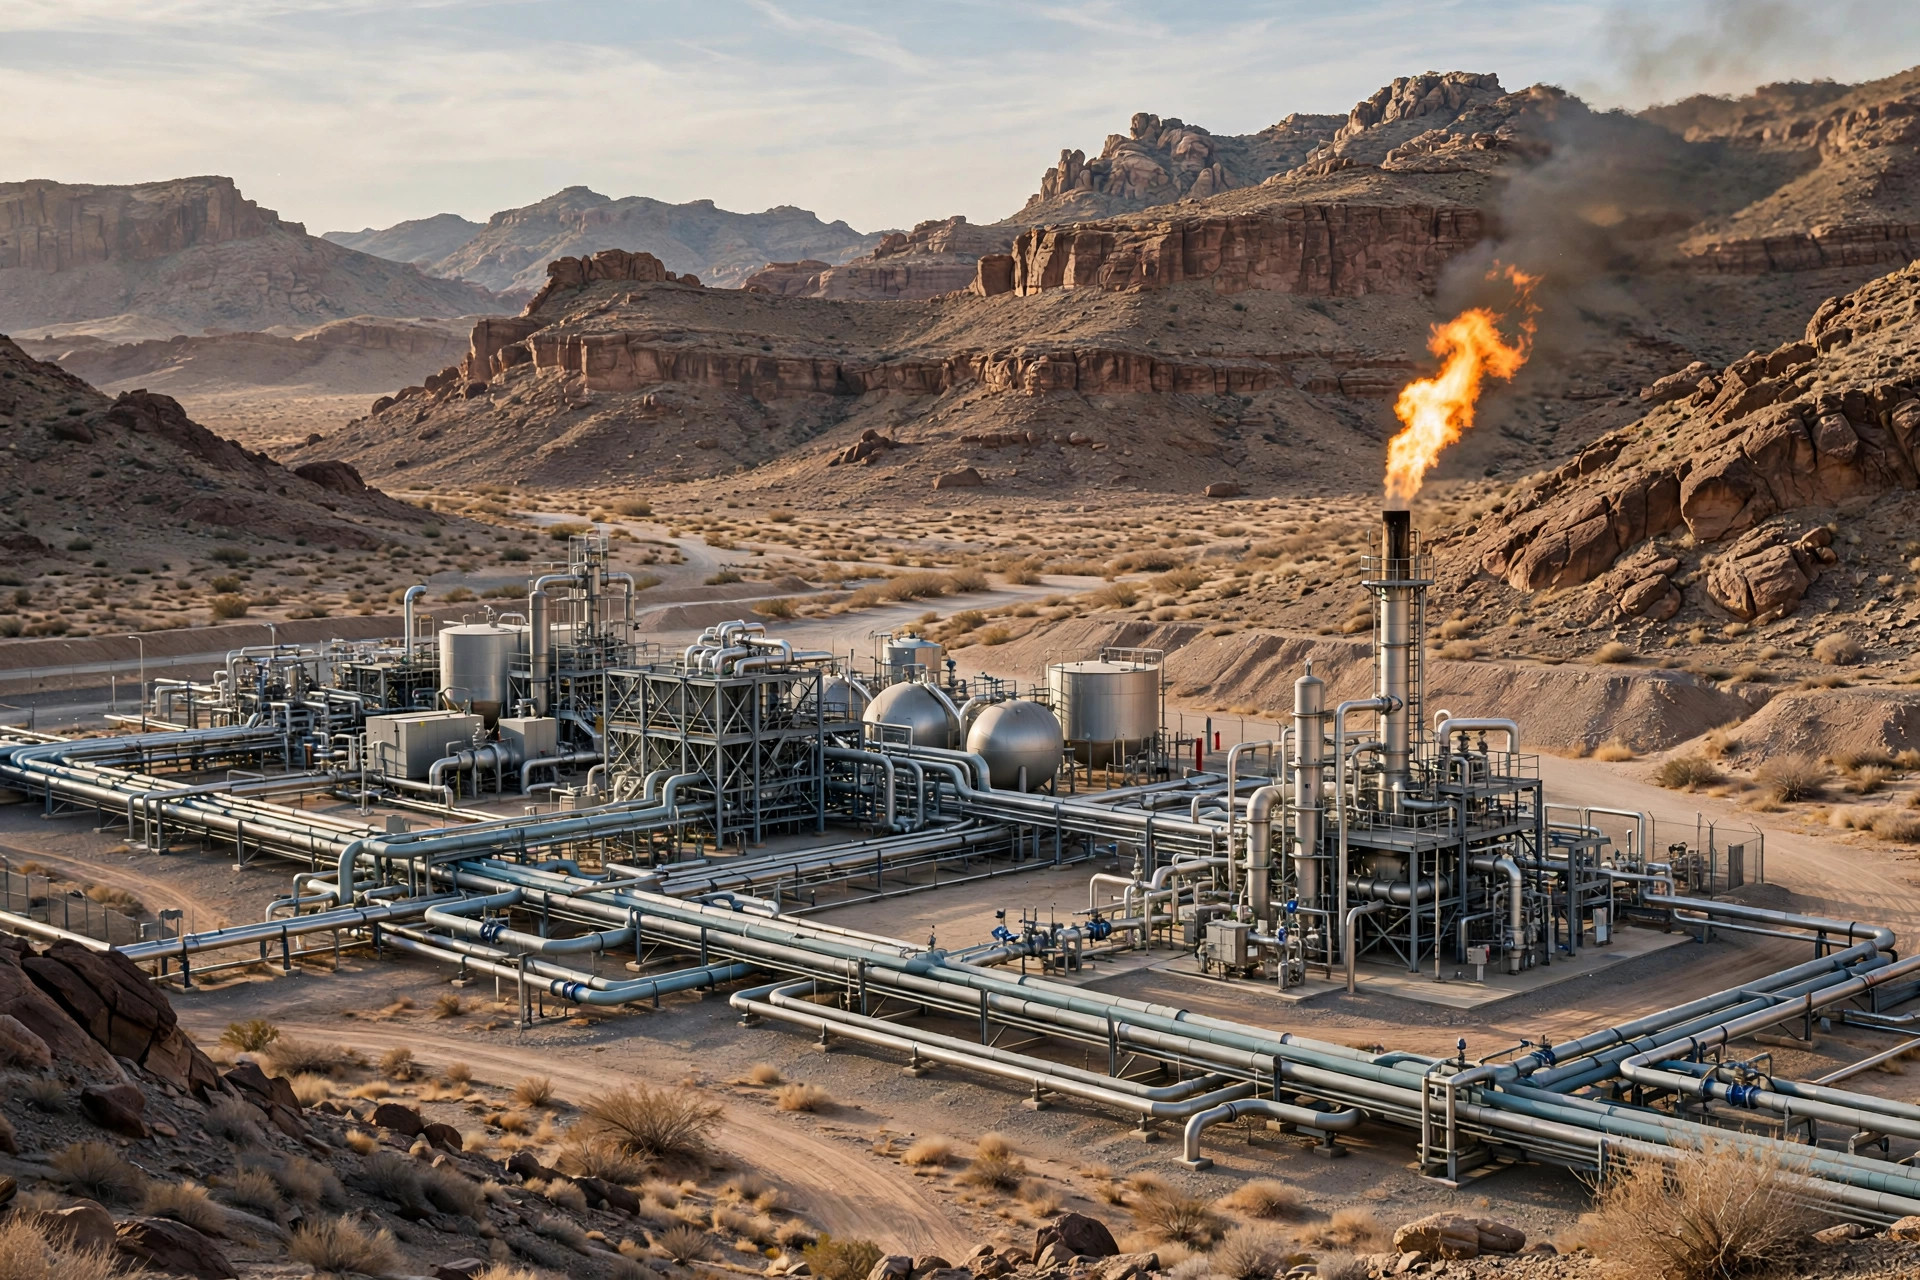
OGDC is an exploration and production (E&P) company, sometimes called an "upstream" company. Upstream is the start of the oil and gas chain: searching for deposits, drilling wells, and bringing crude oil, natural gas and liquefied petroleum gas (LPG) to the surface. OGDC does not refine petrol, does not run filling stations and does not sell gas to your home. Those are downstream and midstream jobs done by refineries, oil marketing companies and gas utilities. OGDC's customers are those businesses: refineries buy its crude, gas utilities and industrial users buy its gas, and distributors buy its LPG.
The distinction matters for how the company earns. A refinery's profit depends on the gap between crude prices and product prices. An oil marketing company's profit depends on regulated margins and inventory movements. An E&P company's profit depends mainly on three things: how much it produces, the price formula it is paid under, and what it costs to find and lift each barrel or unit of gas. Our wider guide to exploration and production stocks on the PSX sets OGDC alongside its listed peers, and the PSX energy stocks overview covers the full chain from wellhead to petrol pump.
The raw material: concessions, reserves and wells
Oil and gas under Pakistani soil belong, ultimately, to the state. Companies operate under licences and concessions granted by the government, which set out who may explore a defined block of land, for how long, and on what financial terms. OGDC holds a large portfolio of exploration licences and producing leases across the country — in Sindh, Punjab, Khyber Pakhtunkhwa and Balochistan — some operated by itself and others held jointly with partners, including other Pakistani E&P companies and, in some blocks, foreign firms.
Inside those blocks sits the company's real asset: reserves, the quantities of oil and gas that geological surveys and drilling indicate can be produced commercially. Reserves are estimates, not warehouse stock. They are revised as wells are drilled, as fields deplete and as prices change what counts as economic to extract. A company's reserve life — roughly, reserves divided by annual production — tells investors how long today's production could continue without new discoveries. Every E&P company is therefore in a race against its own depletion: each barrel sold is a barrel that must eventually be replaced by exploration success, or the business slowly shrinks.
How the revenue line is built
OGDC sells three main products, each with its own pricing logic:
- Natural gas is usually the largest revenue contributor by volume of activity. Gas from each field is sold at a wellhead price set under the petroleum policy and pricing notifications applicable to that field's concession. Crucially, wellhead gas prices in Pakistan are linked to international crude oil prices and expressed with reference to the US dollar. When global oil prices rise, or the rupee weakens against the dollar, the rupee price OGDC receives per unit of gas tends to rise too — even though the gas itself never leaves Pakistan.
- Crude oil and condensate are sold to local refineries at prices derived from international crude benchmarks, adjusted for quality and transport, and again effectively dollar-linked. A stronger oil price or a weaker rupee lifts this revenue line in rupee terms.
- LPG, extracted from gas streams, is sold at prices influenced by international LPG benchmarks and domestic regulation.
Put together, this gives OGDC a distinctive financial personality: its revenues are substantially dollar-linked while a large share of its costs — salaries, local services, many supplies — are in rupees. That is the same broad shape as an exporter's model, and it is why E&P earnings often hold up in periods when the rupee is under pressure. There is a flip side, explored below: dollar linkage also means earnings fall when global oil prices fall, whatever the exchange rate does.
A worked example of one unit of gas
Strip the model to its bones with an illustrative example (the figures are round and invented for explanation, not OGDC's actual prices). Imagine a field producing gas sold at the equivalent of Rs 1,000 per unit. From that Rs 1,000, the company must first pay a royalty to the government — royalty on oil and gas production in Pakistan is a percentage of the wellhead value, set by the applicable petroleum policy. Then come the direct costs of production: well maintenance, compression, field staff, repairs — say Rs 250 per unit in this example. What remains must cover head-office costs, the depreciation of past drilling, exploration spending on new blocks, financing costs and, at the end, corporate tax. What survives all of that is profit.
Two lessons hide in that simple stack. First, the state's take is layered: royalty off the top, taxes at the bottom, plus the fact that the government is also the majority shareholder receiving the biggest share of any dividend. Second, because many costs are fixed per field rather than per unit, profit is highly sensitive to price. If the realised price rises from Rs 1,000 to Rs 1,200 while costs stay near Rs 250, almost all of the extra Rs 200 drops toward profit. If the price falls to Rs 800, profit compresses just as fast. This operating leverage is why E&P profits swing so sharply with oil prices.
The cost side: drilling is a lottery you pay for upfront
Exploration is the industry's great gamble. A company spends heavily on seismic surveys — essentially ultrasound images of underground rock — and then on drilling exploratory wells that may find nothing. A dry well's cost is largely written off. Successful wells, development drilling and production facilities are capitalised and depreciated over the field's life. OGDC's annual capital expenditure is therefore substantial and lumpy, and its results can include exploration write-offs in years when drilling disappoints, alongside occasional large discoveries that add years of reserves.
Production itself declines naturally: most fields produce less each year as pressure falls, unless the company invests in workovers, compression and new wells in the same field. Watching an E&P company's production trend and its reserve replacement — how much new reserve its drilling adds compared with what it produced — is the closest thing to watching a factory's order book. Persistent decline without discoveries means a shrinking business, whatever the oil price does.
Joint ventures: sharing risk, sharing output
Many fields are too large or too risky for one balance sheet, so E&P companies work in joint ventures. Each partner holds a working interest — say 50 per cent or 25 per cent — pays that share of costs and takes that share of production and revenue. One partner, the operator, runs the field day to day. OGDC operates many of its areas and is a non-operating partner in others, including blocks operated by fellow listed companies. For a reader of accounts, this is why you will see references to dozens of named fields and blocks: the company is really a portfolio of interests in many fields at different stages — some exploring, some ramping up, some in long decline — and the portfolio effect smooths, but never removes, the risk of any single well.
The receivables problem: selling to a system short of cash
There is a Pakistan-specific wrinkle that every OGDC follower must understand. Its biggest gas customers are the state-linked gas utilities, and its crude goes to refineries — businesses embedded in the same energy sector that suffers from circular debt, the chain of unpaid bills running through Pakistan's power and gas sectors. When customers pay late, OGDC's profit-and-loss account can look healthy while its balance sheet fills with receivables: gas delivered and invoiced, cash not yet received. Earnings are real in an accounting sense, but dividends, investment and tax all need cash, and cash is what arrives late.
This is why experienced readers of OGDC's reports track two numbers together: profit, and operating cash flow. In good collection periods the two move together. When sector arrears build, profit outruns cash, and the gap sits in trade debts on the balance sheet. Periodic government settlements of circular debt can release large catch-up payments, which is one reason OGDC's cash position and dividend capacity can improve suddenly without any change in production. The same receivables dynamic affects its power-sector peer discussed in our guide to how Hubco makes money — the two companies sit at opposite ends of the gas-to-electricity chain but share the same collection risk.
Where the profit goes: tax, the state and the dividend
After royalties, costs and depreciation, OGDC pays corporate tax and sector-specific levies under the fiscal terms of its concessions, and contributes to development and training funds required of petroleum companies. The remaining profit belongs to shareholders, and here ownership shapes behaviour: the Government of Pakistan holds the majority of OGDC's shares, with the rest held by institutions and the public through the PSX (the company also has a long-standing listing of depositary receipts in London).
OGDC has historically paid regular cash dividends, and because energy earnings are dollar-linked, its payouts have often looked generous beside rupee-earning companies in weak-currency years. Nothing about that is guaranteed: dividend decisions rest on board approval, cash actually collected, capital spending plans and the state's own fiscal appetite as majority owner. If you are learning how payouts reach your account, our guide to how PSX dividends work walks through announcements, book closures and CDC credit step by step.
What moves OGDC's earnings — the short list
- International oil prices, because both crude realisations and dollar-linked gas wellhead prices key off them.
- The rupee–dollar exchange rate: a weaker rupee raises the rupee value of dollar-linked revenue faster than it raises mostly-rupee costs.
- Production volumes: natural decline, maintenance shutdowns, new wells and discoveries all feed straight into revenue.
- Exploration results: discoveries add reserves and future revenue; dry wells add write-offs.
- Collections: the speed at which gas utilities and refineries pay determines cash, and therefore dividend headroom.
- Policy changes: new petroleum policies, pricing notifications, royalty or tax changes can reset the economics of existing fields, and gas pricing reforms in particular are a recurring theme in Pakistan's energy debates.
How to think about the company as an investor
None of this is a recommendation — it is a reading framework, and this article is educational content, not financial advice. A useful habit is to separate OGDC's story into the parts management controls (drilling success, cost discipline, production from existing fields) and the parts it does not (oil prices, the exchange rate, sector payment behaviour, state policy). Compare that with a bank such as HBL, whose earnings hinge on interest rates and lending, or with Meezan Bank's Islamic model, and you start to see why a portfolio holds different business models: they respond to different weather. The Aktzien learning library covers the basics behind all of them, from what a share is to how dividends are taxed.
Reading OGDC's accounts like a field engineer
A few habits separate a careful reader of E&P results from a headline-skimmer. First, production is reported in barrels of oil equivalent and in physical units for each product — watch the trend by product, because a gas-heavy quarter and an oil-heavy quarter have different revenue values. Second, the annual report's reserves statement is the company's real inventory account: note whether exploration replaced what was produced, and how many years of reserves remain at current output. Third, scan the receivables and the cash line before the profit line; in this sector, the order matters. Fourth, separate exploration write-offs — the cost of the lottery tickets that did not win — from underlying operating cost, so a single disappointing well does not disguise a healthy producing business. Finally, remember the portfolio: dozens of fields, each with its own pricing vintage under successive petroleum policies, means OGDC's average realised price is a blend no single headline number captures.
Key takeaway: OGDC finds and produces oil and gas, sells it at regulated but dollar-linked prices, pays royalties and tax to the state, and lives with two permanent swings — global energy prices and how fast Pakistan's energy sector pays its bills.