KARACHI: Every litre of petrol pumped in Pakistan starts as crude oil in a tanker, and somewhere between the port and the pump sits a refinery — an industrial plant that boils, cracks and cleans that crude into petrol, diesel, jet fuel, furnace oil and bitumen. Refining is one of the oldest heavy industries in the country, and its listed companies are among the most misunderstood on the Pakistan Stock Exchange. Their profits can swing violently from quarter to quarter even when they sell roughly the same volume, because a refinery does not really sell fuel in the way a shop sells soap. It sells a spread. Understand that spread, the age of the plants that produce it, and the government policy that shapes it, and refinery stocks stop looking random.
What a refinery actually does
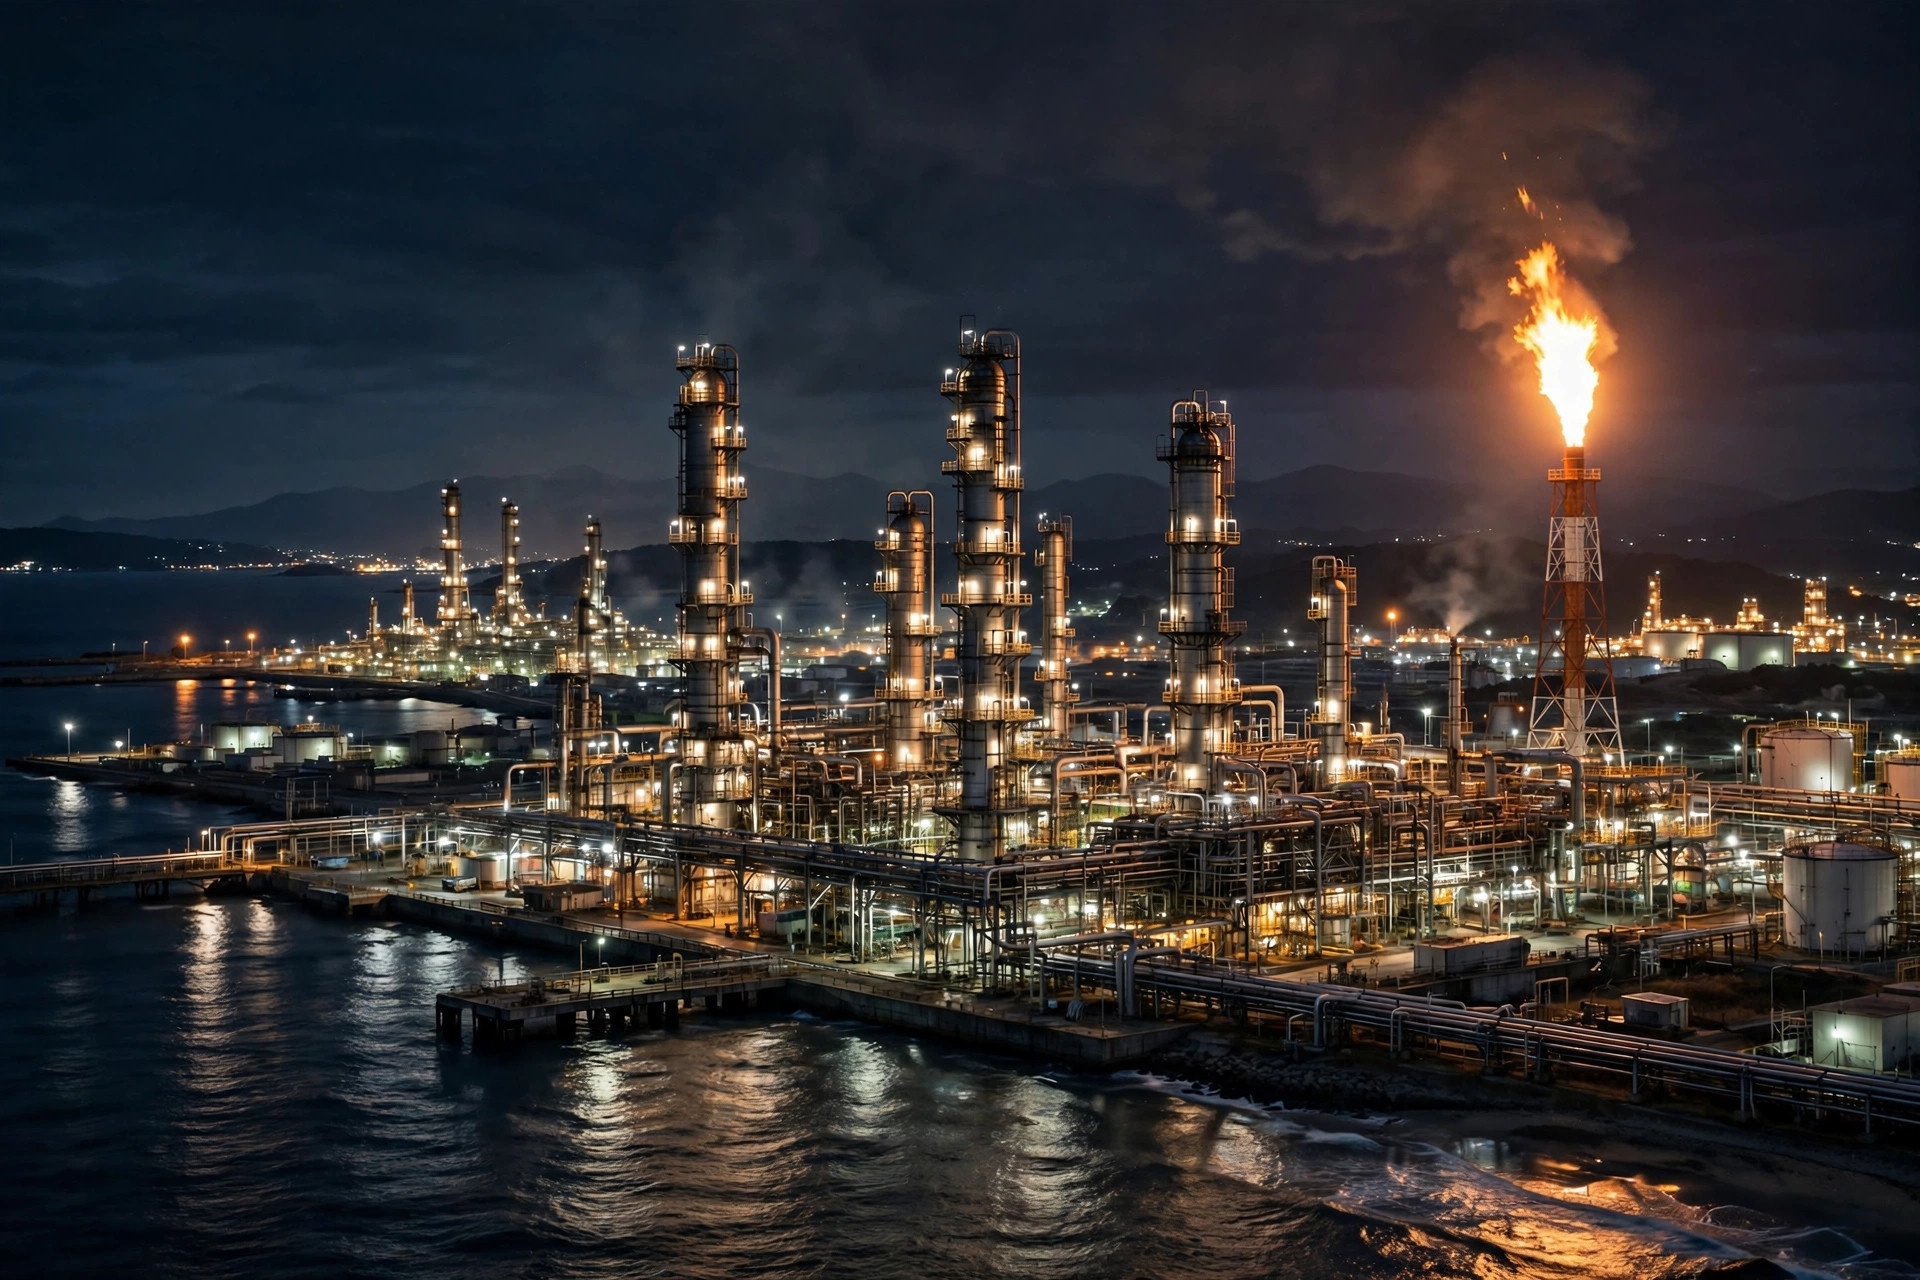
Crude oil is a mixture. A barrel contains light molecules that become petrol and LPG, middle molecules that become diesel and jet fuel, and heavy residues that become furnace oil and asphalt. A refinery separates and upgrades those fractions. The simplest plants mostly distil crude — heat it, let each fraction condense at its own temperature, and sell what comes out. More complex plants add cracking and reforming units that break heavy, low-value molecules into lighter, high-value ones. That difference in complexity is the single most important fact about any refinery, because the output mix determines what each barrel earns.
Pakistan’s refining fleet is small by regional standards and was largely built decades ago. The listed names investors encounter include Pakistan Refinery, National Refinery, Attock Refinery and Pak-Arab Refinery’s listed peers in the wider energy chain, alongside newer entrants and expansion projects that appear in market discussion from time to time. Their locations matter: coastal plants near Karachi can receive large crude tankers directly, while the up-country refinery at Rawalpindi is supplied by pipeline and serves northern demand. Plants differ in design crude, capacity and complexity, so no two experience the same market in quite the same way.
A refinery’s customers are the oil marketing companies, which buy finished petrol and diesel, blend and transport it, and sell it through pump networks — the subject of our guide to oil marketing companies. Airlines and power plants have historically bought jet fuel and furnace oil directly or through marketers. As Pakistan’s power sector shifted away from furnace oil towards gas, LNG, coal and renewables, the market for the heaviest refinery output shrank — a structural problem we return to below, because a simple refinery cannot simply choose not to produce its heavy fraction.
The gross refining margin: the whole business in one number
Analysts summarise a refinery with the gross refining margin, or GRM: the value of the products made from a barrel of crude, minus the cost of that barrel, before operating costs. Imagine, purely as an illustration, that a barrel of crude costs the equivalent of Rs 25,000 and the petrol, diesel and other products refined from it sell for a combined Rs 27,000. The gross margin is Rs 2,000 per barrel. If product prices rise faster than crude, the margin widens; if crude jumps while pump prices lag, it can compress to nothing or turn negative. Multiply that swing by millions of barrels and you see why refinery earnings are so volatile.
Several forces move the GRM. Global product prices — often tracked against regional benchmarks in Singapore and the Gulf — move with worldwide demand, refinery outages, wars and shipping disruptions. Crude grades matter too: heavier, cheaper crude can be a bargain for a complex plant that can upgrade it, and a burden for a simple plant that cannot. The exchange rate overlays everything, because crude is bought in dollars while a large share of local product pricing is set in rupees through regulated or semi-regulated formulas. A sharp rupee depreciation can inflate the rupee value of inventories one quarter and squeeze working capital the next.
Then there are inventory gains and losses, the accounting echo of the margin. A refinery holds weeks of crude and product in tanks. If prices rise while that stock sits there, the company books an inventory gain; if prices fall, an inventory loss. These are not cash earned from better operations — they are timing effects — yet they can dominate a quarterly result. Experienced readers of refinery accounts therefore separate the underlying refining result from inventory effects before drawing any conclusion, much as they do when reading our explainer on exploration and production stocks, where dollar-linked prices create a different kind of swing.
Ageing plants and the furnace-oil problem
Age is not just a number for a refinery. Older, simpler configurations were designed for a Pakistan that burned large quantities of furnace oil in power stations. That demand has faded as policy pushed cheaper and cleaner generation. The heavy residue, however, still comes out of the crude barrel. If nobody wants it at a good price, the plant must sell it at a discount, store it, or cut runs. Tanks fill up, and Pakistani refineries have at times had to reduce throughput or arrange special exports of surplus furnace oil. A product slate built for yesterday’s market is the sector’s defining handicap.
Complexity is the cure, and it is expensive. Upgrading means adding units that convert residue into diesel and petrol, remove sulphur to meet modern fuel specifications, and improve energy efficiency. Such projects cost very large sums, take years, and must be financed in an economy where interest rates have often been high. This is why refinery managements and the government have negotiated for years over an upgrade framework: the companies argue they cannot fund modernisation from thin, volatile margins alone, while the state wants cleaner fuels, less import dependence and no open-ended subsidy.
Fuel quality is part of the same story. Pakistan has progressively moved towards Euro-V specification petrol and diesel, which limits sulphur and improves air quality. Meeting tighter specifications either requires upgraded units or blending with imported finished product — which undercuts the point of refining locally. When you read a refinery announcement about a shutdown, a turnaround or a new unit, translate it into one question: does this change the product slate towards the lighter, cleaner fuels the market actually wants?
Refinery policy: incentives, deemed duty and upgrades
Refining in Pakistan has never been a fully free market. Prices of key products have historically been linked to import-parity formulas — what it would cost to land the same fuel from abroad — because Pakistan imports both crude and finished products and the pricing system tries to treat them consistently. Embedded in that history is the idea often called deemed duty: a component built into prices in earlier policy eras, intended to help refineries fund upgrades. Whether that money produced upgrades fast enough has been debated by auditors, courts and commentators for years, and the debate explains why newer policy frameworks tie benefits more explicitly to signed upgrade agreements and milestones.
The Brownfield Refinery Policy approved in recent policy cycles — readers should check the Petroleum Division and OGRA for the current, authoritative version — aimed to unlock exactly those upgrades, offering fiscal incentives in return for committed modernisation, while a separate greenfield policy sought new large refineries. Policy in this sector changes through formal approvals and sometimes stalls between announcement and implementation, so treat headlines cautiously: an incentive announced is not yet cash in a company’s accounts, and an upgrade agreement signed is not yet a plant built. The investment case, such as it is, lives in the distance between those stages.
Working capital is the quieter policy-adjacent risk. Refineries buy crude in dollars on short credit lines, hold large inventories, and sell onward in rupees. Letters of credit, exchange-rate jumps and banking limits have at times constrained crude imports nationally — during foreign-exchange stress, opening LCs for any importer, refiners included, became difficult. A plant can be technically sound and still run below capacity because the financial plumbing around it is squeezed. That is a Pakistan macro risk as much as a company risk.
How to read a refinery result
Start with throughput: how much crude did the plant actually process relative to its capacity? Low utilisation spreads fixed costs over fewer barrels. Next, separate the reported profit into the refining result and inventory effects, using the notes and management commentary. Then check the product mix discussion — diesel and petrol realisations versus furnace oil — and any statement on GRM direction. Finally, look at the balance sheet: crude payables, borrowings and the cash cost of carrying inventory, especially after a depreciation.
A worked example shows why caution matters. Suppose, illustratively, a refinery processes 100,000 barrels in a period and the GRM improves by the rupee equivalent of Rs 300 per barrel. That is Rs 30 million of extra gross margin — meaningful, but a single inventory swing on a large tank farm can be several times that size in either direction. Headline profit doubling or halving year on year is therefore normal in this sector and tells you little until you decompose it. Compare several periods, not one dramatic quarter.
Dividends in refining tend to follow the same cycle: generous after strong-margin years, thin or absent when margins or upgrade spending bite. Investors who need steady income should notice that pattern rather than extrapolate a good year. Readers who want the broader energy picture can start from our sector overview in PSX energy stocks and the Aktzien learning library.
Risks that never fully go away
Global margin cycles are outside any Pakistani management’s control. Local risks add to them: unplanned shutdowns at ageing plants, safety and environmental incidents, disputes over pricing formulas, delays to upgrade incentives, and the long-run question of how fast transport electrification and fuel-efficiency erode petrol and diesel demand growth. None of this makes the sector uninvestable or investable by itself — it makes it a sector where position size and expectations should reflect genuine cyclicality. This article is educational content, not financial advice, and it deliberately offers no view on any individual refinery share.
Turnarounds, shutdowns and reading the calendar
Refineries also live by a maintenance calendar that beginners often mistake for news. Every few years a plant shuts major units for a turnaround — weeks of inspection, cleaning, catalyst replacement and repair that stop production and cost heavily, but without which reliability and safety decay. Planned shutdowns are disclosed in advance and their cost is the price of the next years of runs; unplanned shutdowns, caused by equipment failure, power interruptions or crude supply breaks, are the genuinely bad kind, and the market disclosure language usually distinguishes the two if read carefully. Seasonal patterns overlay this: demand for diesel peaks with harvests and transport seasons, petrol demand rises in summer travel, and furnace-oil demand — what remains of it — concentrates in shortage periods when gas is curtailed to power plants.
Crude sourcing is another under-read section of refinery reporting. Pakistani refineries process a blend of imported crude, mostly from the Gulf, and domestic crude and condensate delivered from local fields. Domestic crude is priced under its own arrangements and arrives by pipeline and bowser logistics that constrain volumes; imported crude brings the letter-of-credit and shipping exposures described earlier. The blend matters because each plant was designed around particular crude characteristics — a refinery fed a diet far from its design crude will produce a worse product slate at worse energy cost, whatever the headline GRM environment. When a refinery announces supply arrangements or crude-slate changes, it is telling you something real about future margins.
Finally, environmental and safety compliance is moving from footnote to cost line. Fuel-quality standards tighten, emissions and effluent rules are enforced with growing attention, and ageing plants anywhere in the world carry incident risk that can stop operations and trigger liabilities in a single day. None of this appears in a price-to-earnings ratio until, suddenly, it is the only thing in it.
One more habit separates careful refinery watchers from casual ones: they read across the fence. A refinery’s crude costs appear in the exploration companies’ realised prices; its product prices are set beside the oil marketing companies’ margins; its inventory swings echo global benchmarks quoted in dollars. No refinery result is fully explained inside its own press release, and the hour spent cross-checking the energy chain’s announcements against each other is the cheapest research an investor in this sector can do.
Key takeaway: a refinery earns a volatile spread between crude and products; plant complexity, the furnace-oil overhang and upgrade policy decide who captures that spread — so always strip out inventory effects before judging a result.