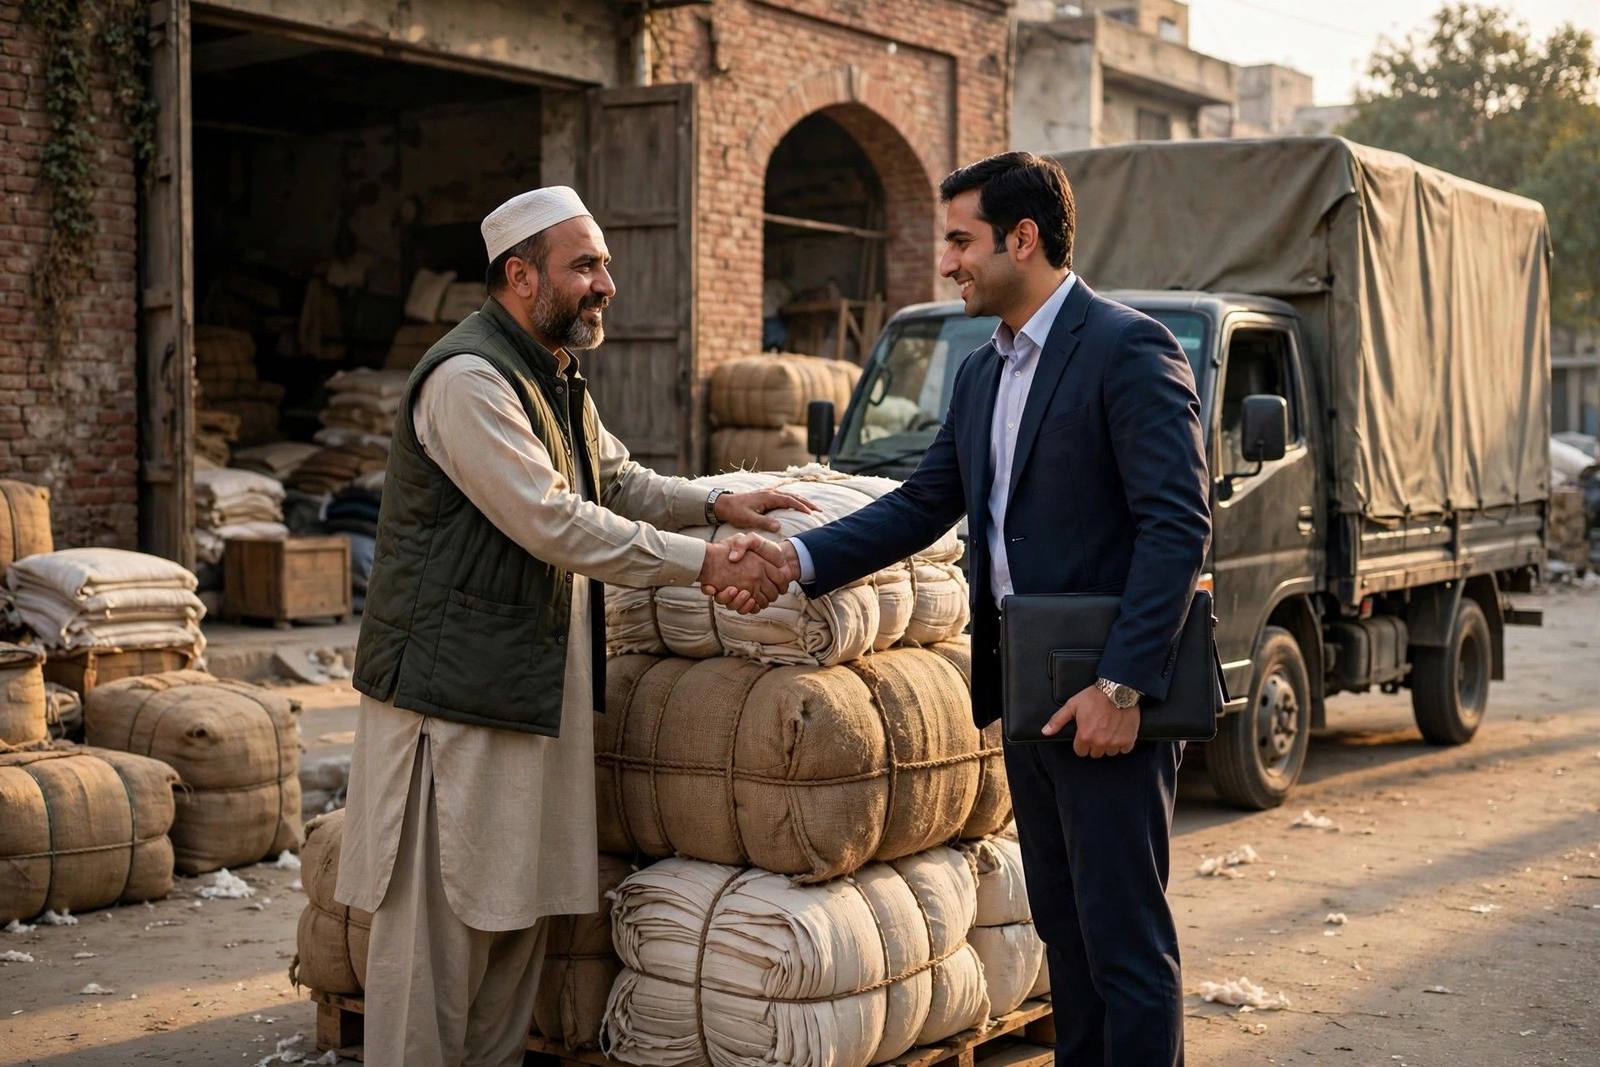
KARACHI: Open an Islamic bank's brochure and the products wear friendly names — car financing, home financing, running finance for business. Open the actual agreement and a different vocabulary appears: murabaha, ijara, musharaka, mudaraba, salam, istisna. These are not marketing labels. They are classical contracts, each with its own rules about who owns what, who bears which risk, and where the bank's profit legitimately comes from. Because interest — riba — is prohibited, an Islamic bank cannot simply lend money and charge for time. It must instead buy, lease, build or co-own something real, and earn from trade, rent or partnership. This guide walks through the main contracts one by one, shows which Pakistani products each one powers, and explains the honest criticisms each attracts.
The design rule underneath them all
Every mode in this guide is an answer to the same design problem: how does a financier earn a return without a loan at interest? The classical answers fall into three families. Sale-based contracts let the bank buy an asset and sell it on at a disclosed profit, paid in instalments. Lease-based contracts let the bank own an asset and rent out its use. Partnership contracts let the bank put capital alongside the customer's and share the outcome, profit and loss alike. Layered over all three is a discipline that regulators and Shariah boards insist on: the bank must genuinely own the asset, and bear ownership risk, for at least the moment the contract requires. A financing in which the bank never owns anything, bears no risk and simply books a markup is, in the critics' phrase, a loan wearing a costume — and the entire compliance apparatus of the industry, described in our guide to Islamic banking in Pakistan, exists to police the difference.
Murabaha: the cost-plus sale that runs the industry
Murabaha is the workhorse. A customer identifies something the business needs — raw material, inventory, machinery. The bank buys it from the supplier, taking title itself, then sells it to the customer at the purchase cost plus a disclosed profit margin, payable in deferred instalments. The customer's obligation is a price, fixed at the moment of sale, not a loan balance that grows with time; late payment cannot lawfully increase the price, though contracts may direct a stated amount to charity as a deterrent, and compensation for actual loss is handled under rules set by the central bank and Shariah board.
Two features make murabaha commercially irresistible, and also controversial. Its cash flows are predictable — fixed instalments over a set term — which makes it easy for banks to price, using market benchmarks such as KIBOR as a reference for the margin even though the contract is formally a sale. And its risk to the bank is low once the sale is made. Critics within Islamic finance have long argued that an industry leaning too heavily on murabaha and its cousins reproduces the economics of conventional lending while adding paperwork, and that the partnership modes express the system's spirit better. Defenders reply that a genuine sale, with genuine ownership and a fixed price, is legally and ethically distinct from a loan — and that customers who want payment certainty are entitled to choose it. For the customer, the practical questions are concrete: what is the total price over the term, what happens on early settlement, and is any rebate on the remaining markup given?
Ijara: leasing where the bank really is the landlord
Ijara is a lease. The bank buys an asset — a car, a machine, a building — and rents it to the customer for a term, retaining ownership throughout. Rent is the price of using the asset, and because the bank remains the owner, the responsibilities of ownership sit with it in ways a lease contract must spell out: major maintenance and ownership risks are, in principle, the lessor's, while routine care is the lessee's. At the end of the term the asset may be transferred to the customer through a separate gift or sale arrangement — crucially, under classical rules, not as a clause that makes the lease itself a disguised instalment sale.
Pakistani savers meet ijara in two big places. Car financing from Islamic banks is commonly structured as ijara, which is why the customer's documents speak of rentals rather than instalments of principal and interest — compare the conventional structures described in our guide to car financing in Pakistan. And ijara is the contract behind many sukuk: investors own a share of an asset, lease it to the issuer, and receive rent as their return, as described in our guide to sukuk and government securities. The distinction to hold onto is ownership: in a true ijara the lessor's return is earned by owning something useful and bearing an owner's risks, not by renting out money.
Musharaka: partnership, including the house-buying kind
Musharaka is a partnership: two or more parties contribute capital to a venture and share profit in agreed proportions, while losses fall strictly in proportion to capital contributed. It is the mode reformers point to when they describe what Islamic finance is for — finance tied to real enterprise, with the financier's return dependent on the venture actually succeeding. A bank entering musharaka with a business shares its fate rather than standing outside it with a fixed claim, which is precisely why the mode demands more monitoring, more trust and more honest bookkeeping than a sale contract, and why it remains a modest share of industry financing in practice.
Its most familiar Pakistani form is diminishing musharaka, the standard structure behind Islamic home financing. Bank and customer jointly buy the house: the bank might own the larger share, the customer the smaller. The customer then pays rent on the bank's share — rent that falls as the share shrinks — while buying out units of the bank's ownership with each payment, until the house is wholly theirs. The elegance is real: payments naturally combine rent and purchase, and the bank earns from an asset it genuinely co-owns. The consumer questions are equally real: how is the rent on the bank's share set and reviewed, how are the buyout units priced, and what are the total payments over the full term compared with alternatives, including conventional mortgage offers?
Mudaraba: the contract behind your deposit account
Mudaraba completes the core set, and it is the mode savers participate in without noticing. One party, the rabb-ul-mal, provides capital; the other, the mudarib, provides work and expertise; profit is shared in a pre-agreed ratio, and financial loss falls on the capital provider unless the manager was negligent or breached the terms. Islamic bank deposit accounts are built on it: depositors' money is pooled and invested by the bank as mudarib in the bank's pool of murabaha, ijara and partnership assets, and the profit actually earned is shared between depositors and bank in declared ratios, with weights assigned by account type and balance. That is why Islamic deposit returns are announced as expected or indicative rates and settled as declared rates after the period closes — legally, they cannot be a guaranteed interest payment.
The same contract powers Islamic mutual funds and the investment side of takaful, where the operator manages participants' money as mudarib. It also explains a feature newcomers find odd: if the pool genuinely loses money through honest investment, the depositor's capital is not contractually guaranteed by the mudaraba itself — one reason regulators supervise these pools closely, banks manage them conservatively, and profit-equalisation reserves are used to smooth declared rates between good and lean periods.
In practice, a murabaha financing unfolds as a choreography that compliance teams audit step by step. The customer signs a promise to purchase, the bank appoints — in many Pakistani structures — the customer as its agent to physically procure the goods from the supplier on the bank's behalf, title and risk pass to the bank, and only then is the murabaha sale executed at the disclosed cost-plus price, with payment scheduled in instalments. The sequence sounds like pedantry until something goes wrong before the sale is executed: goods damaged in transit, for instance, are the owner's problem, and at that moment the owner is the bank. Structures in which the bank's ownership is instantaneous and riskless by construction are exactly what Shariah audits probe, and banks maintain warehouses, inspection reports and insurance — takaful, naturally — over the goods they momentarily own. For the customer, the visible difference from a loan is small; the legal difference determines everything from what happens on default to how the transaction is taxed and accounted for.
The supporting cast: salam, istisna, wakala and sukuk structures
Four more names round out a working vocabulary. Salam is a forward sale with full advance payment: the bank pays now for specified goods — classically agricultural produce — to be delivered later, financing the farmer's season without a loan. Istisna is a commission to manufacture or construct: payment staged against progress, used for project and asset finance where the thing being financed does not yet exist. Wakala is simple agency — one party acts for another for a fee — and appears everywhere from takaful operations to investment accounts where a bank appoints an agent. Sukuk, finally, are certificates representing ownership in assets or ventures structured through these contracts; Pakistan's government ijara sukuk, leased against state assets, are the backbone of the domestic Islamic capital market, including the green issuance covered in our guide to green sukuk.
Mudaraba also explains a feature of Pakistani banking that puzzles depositors every profit season: two Islamic banks can declare noticeably different returns on similar accounts in the same month. Each bank's pool holds a different mix of assets booked at different times — a pool heavy with older, lower-priced murabaha earns less than one freshly invested at high market rates — and each applies its own agreed profit-sharing ratio and weightages between account types. The State Bank's disclosure rules push banks to publish their pool management, weightages and declared rates precisely so depositors can compare like adults rather than by rumour. A depositor who understands the contract reads those tables as the product itself; a depositor who expects interest with an Arabic name will always feel vaguely cheated, in good months and bad.
The benchmark question deserves its own honest paragraph, because it is the criticism outsiders raise first: if a murabaha margin or an ijara rental is priced by reference to KIBOR, is the result not simply interest by another name? The industry's answer distinguishes the benchmark from the contract: using a market index to price a genuine sale or lease no more makes it a loan, scholars argue, than a halal butcher pricing meat by reference to the conventional market makes the meat impermissible — what matters is what is actually traded and who bears ownership risk. Sceptics answer that when every cash flow matches a loan's, the distinction has become one of form over substance, and the debate has pushed standard-setters to encourage profit-rate benchmarks of Islamic finance's own. For a customer the argument has a practical residue: compare total costs openly across Islamic and conventional offers, insist on the contract documents, and judge the Islamic product by whether its structure — not just its price — is one you understand and accept.
Reading any Islamic product in five questions
Whatever the brochure calls a product, the contract underneath can be identified with five questions. What does the bank buy, own or co-own, and when? Where exactly does its profit arise — markup, rent, or a share of an outcome? Is the amount I owe fixed at signing, or can it change, and on what trigger? Who bears the loss if the asset is destroyed, the venture fails or the market falls? And what does the institution's Shariah board say about this structure, in the fatwa and annual Shariah report the bank publishes? A product whose answers are clear, documented and consistent is doing what Islamic finance claims to do. A product whose answers dissolve into "it works just like the conventional one" deserves the scepticism it invites — from customers, and increasingly from scholars and regulators pressing the industry from sale-based comfort toward genuine partnership and asset ownership. This article is educational content, not financial advice.
Key takeaway: Islamic finance replaces the loan with real contracts — murabaha sells at a disclosed markup, ijara rents out an owned asset, musharaka shares a venture's fate, and mudaraba splits the profit between capital and work — so always ask what the bank owns and where its profit arises.