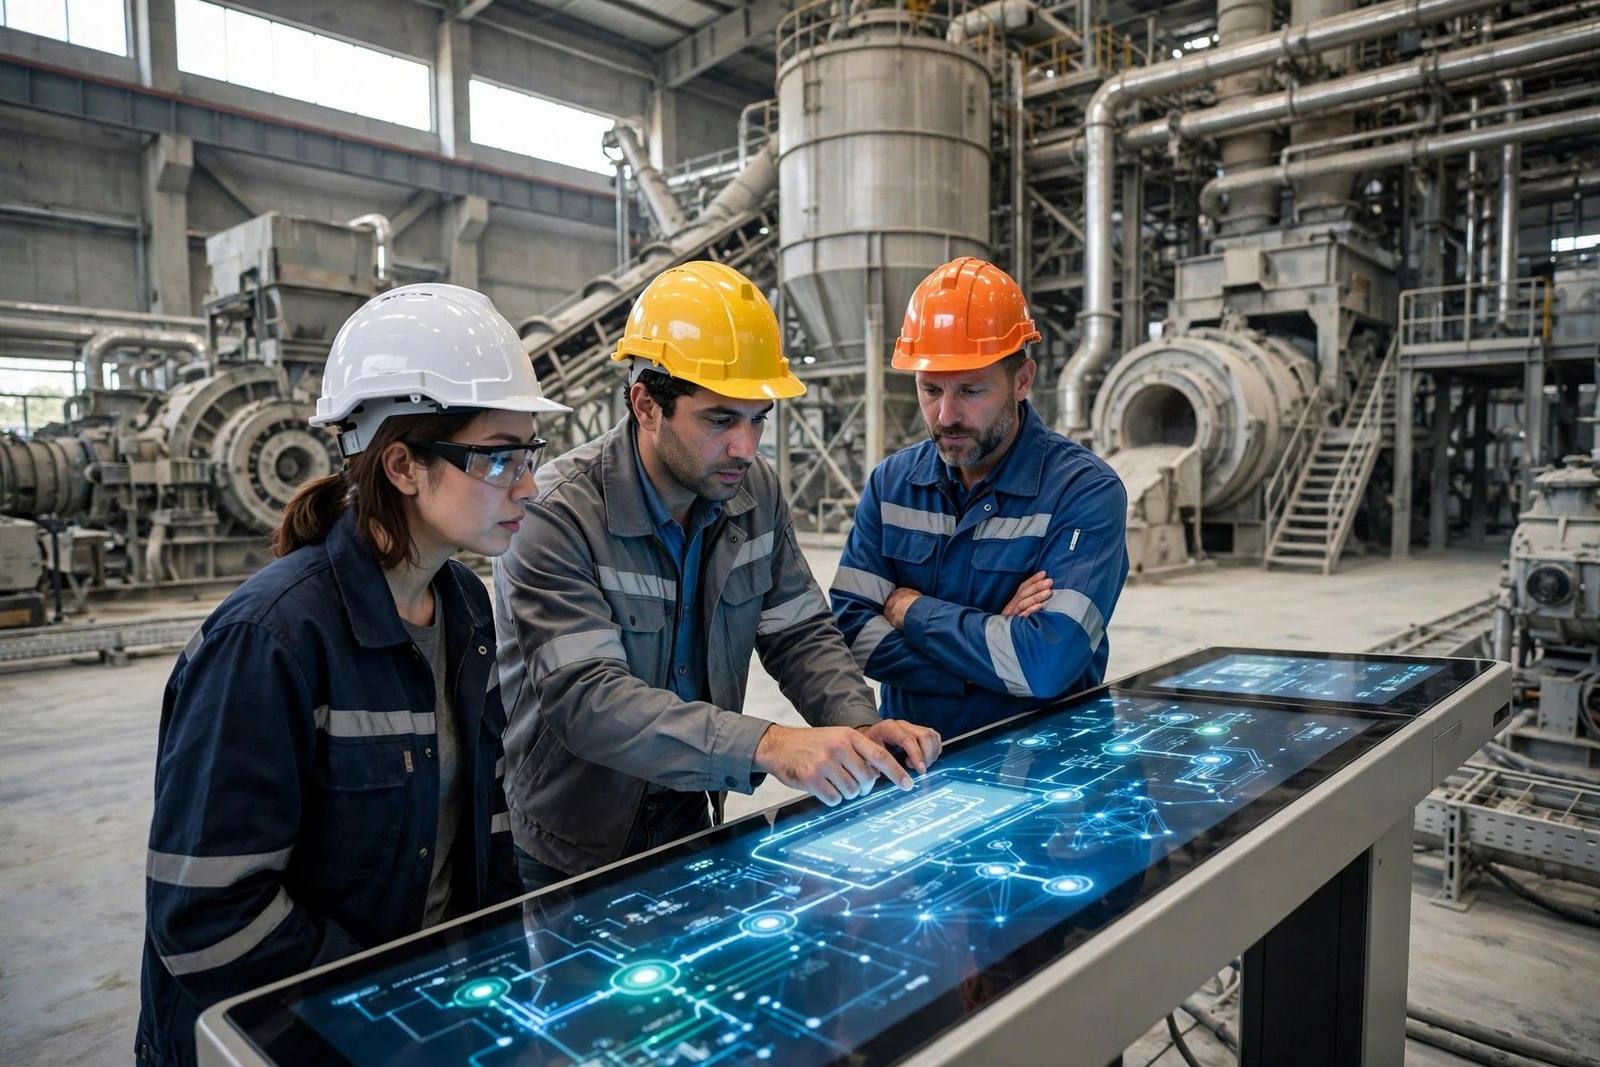
KARACHI: Before the Pakistan Stock Exchange had a technology sector worth the name, it had Avanceon. The Lahore company does not write consumer apps or run call centres; it automates factories — programming the controllers that run cement plants, food factories, refineries and water systems, stitching machines into control rooms, and then maintaining what it built. Its roots reach back to an automation practice started by founder Bakhtiar Hameed Wain in the 1980s, its Pakistani operation began in 1989, and its 2013 initial public offering made it one of the first industrial-technology stories the local market was asked to price. Today the group works across Pakistan and the Gulf, parents the separately listed Octopus Digital, and offers investors something rare on the PSX: a business whose order book is written by the capital spending of heavy industry at home and in the Middle East.
Origins: an engineer's practice becomes a company
Avanceon's own telling of its history starts in 1984, when Bakhtiar Hameed Wain — an engineer who had worked at Exxon Chemicals, Fauji Fertilizer and ICI — founded an industrial automation firm in Exton, Pennsylvania. In 1989 he established the Pakistani operation as Innovative Automation and Engineering Limited, initially focused on programming programmable logic controllers, the rugged little computers that run production lines, and on supporting food and beverage manufacturers. That beginning explains the company's character to this day: it was born on factory floors, not in a software park, and its earliest customers cared about whether a line stopped, not about how elegant the code was.
The present listed company was incorporated in Pakistan on 26 March 2003, taking over and formalising the business, and the Avanceon name replaced the old Innovative Automation and Engineering identity in the years that followed. Through the 2000s the company widened from programming into full system integration — designing control systems, supplying equipment from global principals, installing and commissioning it, and training plant staff — and followed its customers into the Gulf, establishing subsidiaries in Dubai and Qatar that put its engineers within reach of the region's oil, gas and utilities projects.
The stock-market chapter opened in 2013, when Avanceon completed its IPO and listed on the Karachi exchange. Wain himself has pointed to that date proudly: within three years of listing, the company was winning national awards for the quality of its corporate reporting, an unusual priority for a mid-sized engineering firm and a deliberate signal that it intended to be judged as a modern listed company rather than a family workshop. For the PSX, the listing mattered beyond its size — alongside the software exporters in the technology sector, Avanceon gave the market an engineering-led technology name years before the sector became fashionable.
What Avanceon actually does
The cleanest way to understand Avanceon is as a translator between two worlds: the global manufacturers of automation equipment — the control systems, instruments and software platforms made by the likes of Rockwell Automation and other international principals with whom it has long-standing partner relationships — and the plant owners of Pakistan and the Middle East who need those systems designed into a working factory. Avanceon rarely manufactures the core hardware itself; its value lies in engineering design, software configuration, panel building and assembly, installation, testing, commissioning and the long tail of support after handover.
Its reported segments describe the work well. The core business covers application-based solutions, systems and products for process industries — oil and gas, chemicals, cement, fertilisers, food and beverages, pharmaceuticals and water. A specialised business handles energy management and higher-end solutions. After-market support, the segment investors often watch most closely, covers service-level agreements, spares and technical support for installed systems: the recurring, relationship-driven work that continues between big projects. A manufacturing and assembling activity supports the project business, and an engineering services arm exports the group's own engineers — seconding them to the Dubai and Qatar subsidiaries and billing man-hours for design work done in Lahore for projects abroad. That last segment quietly makes Avanceon an exporter of engineering hours in the same spirit as the software houses, a theme our guide to Pakistan's IT and services exports develops.
The customer logic follows from the product. A refinery or a beverage plant cannot tolerate unplanned downtime, and its control system is not a commodity it re-tenders casually; once an integrator knows a plant's systems, it tends to be called back for expansions, upgrades and emergencies. Avanceon's three decades with some of the same industrial groups, in Pakistan and increasingly in Saudi Arabia and the wider Gulf, rest on that accumulated familiarity.
Ownership and the group it has built
Avanceon remains a founder-led company: Bakhtiar Hameed Wain serves as chief executive, with Khalid Hameed Wain as chairman, and the founding family and management form the sponsor core around which the listed company is organised. The operating footprint is held through subsidiaries — Avanceon FZE in Dubai, Avanceon Automation and Control in Qatar, a Saudi energy venture, and, most visibly for PSX investors, Octopus Digital Limited, the industrial-analytics business the group carved out and listed separately in 2021 while retaining control. That makes AVN partly an operating company and partly a holding exposure to its listed subsidiary — a point that matters when comparing its reported earnings with the value the market assigns to the Octopus stake.
How Avanceon makes money
The revenue engine is project work, and project work is lumpy by nature. A typical engagement — automating a new production line, migrating a plant's ageing control system, building an energy-management system across a utility — is contracted at a price, executed over months, and recognised as work progresses. Margins live or die on estimation discipline: the gap between what the engineers promised the sales team the job would cost and what it actually costs to deliver. Equipment supplied as part of a project passes significant revenue through the books at relatively thin margins, while the engineering, software and commissioning hours carry the real profitability — one reason experienced readers of Avanceon's accounts look past the revenue line to gross margin and backlog.
Around the projects sit the stabilisers. After-market support contracts and spares provide recurring income tied to the installed base rather than to new capital spending. Engineering services to the Gulf subsidiaries convert Lahore salaries into foreign-currency-linked earnings. And the order backlog — the contracted work not yet executed — is the single most informative forward indicator the company publishes: a growing backlog today is next year's revenue, while a shrinking one warns of a gap long before it reaches the income statement. Costs are dominated by engineers and project staff, imported equipment priced in foreign currency, and the working capital absorbed by long project cycles, where customers pay on milestones and retention amounts can be held until well after handover.
Strengths, risks and controversies
Avanceon's strengths begin with scarcity: there are few listed, scaled industrial-automation integrators in Pakistan, and fewer still with operating subsidiaries across the Gulf and a track record with both local industrial groups and regional state-linked customers. Its partnerships with global automation principals give it product credibility it could not build alone, its installed base generates the recurring support work that smooths the project cycle, and its reporting and governance have been recognised by the accounting profession's own awards — not a guarantee of anything, but a habit investors notice.
The risks are the mirror image. Project revenue depends on industrial capital spending, which in Pakistan rises and falls with interest rates, the exchange rate and the mood of a handful of large groups; in the Gulf it depends on tendering cycles the company does not control. Receivables from large customers, including public-sector-linked ones, can stretch, and a single disputed project can absorb management attention and cash. Currency moves cut both ways on imported equipment and foreign earnings. And the group's structure — a listed parent with a listed subsidiary and several overseas arms — demands careful reading: consolidated numbers blend businesses with very different rhythms, and minority interests mean not all subsidiary profit belongs to AVN shareholders. Beginners comparing it with a pure software exporter such as NetSol Technologies will find the mechanics closer to a construction-and-engineering firm than to a SaaS business, despite the technology label.
The Gulf second home
Avanceon's expansion map deserves a section of its own, because it explains the earnings mix. The Dubai subsidiary, Avanceon FZE, and the Qatar operation placed the company inside the Gulf's two-decade construction and industrial supercycle: refinery and petrochemical expansions, water and district-cooling utilities, food and consumer plants serving growing cities, and transport infrastructure built for global events. A Saudi energy venture extended the same model into the region's largest economy. The work won there differs from the Pakistani book in two ways investors notice. Ticket sizes are larger and customers are more often state-linked or multinational, which lengthens tendering but strengthens the counterparty; and payment, while slower to arrive through project milestones, is ultimately in the Gulf's hard-currency economies, giving the group's consolidated earnings a foreign-exchange character unusual for a Lahore mid-cap.
The bridge between the two markets is the engineering-services segment: design work, human-machine-interface development, logic design and commissioning support performed by Avanceon's Pakistan-based engineers for the Gulf subsidiaries' projects, and billed between group companies. It is, in substance, an export of engineering hours from a lower-cost base into higher-priced projects — the same arbitrage the software exporters practise, executed by process engineers instead of programmers. It also creates a career escalator that helps the group retain scarce automation talent: a young engineer in Lahore can see a path to site work in Doha or Dubai without resigning, which in a market where Gulf employers recruit aggressively is a retention tool as much as a revenue line.
Reading a project company's accounts. Because Avanceon reports like an engineer and earns like a contractor, it teaches a distinct reading skill. Revenue recognised on percentage-of-completion can rise while cash deteriorates, if milestone billings lag work done; contract assets and retentions receivable — money earned but held back by customers until defects periods expire — are where optimism hides; and a single large Gulf award can dominate an entire year's order intake, making year-on-year comparisons treacherous. Seasoned followers therefore read the backlog disclosure, the segment split between core projects, specialised work, engineering services and after-market support, and the ageing of receivables before they read the profit line. That discipline, learned on AVN, transfers directly to every contractor and EPC-adjacent name a PSX investor will ever meet.
The name on the PSX
AVN trades in the technology and communication sector and has, at times, been a constituent of benchmark indices — a reflection of how few mid-sized industrial-technology names the market has to choose from. It has not historically been a dividend payer of the clockwork kind; its own disclosures through market data providers have long described a reinvestment stance, with cash directed to working capital, Gulf expansion and the listed subsidiary rather than to payouts. Liquidity is that of a mid-cap: tradable in normal conditions, capable of sharp moves on contract announcements, results or news about Octopus, in which the parent's fortunes are partly mirrored.
What kind of investor studies Avanceon
Avanceon rewards the investor who likes industrial cycles and order books: the watchlist is the backlog and its geographic split, the pace of Gulf contract wins, gross margin on project work, receivables and retention balances, the health of after-market support revenue between projects, and the performance of Octopus Digital, whose results feed the parent's consolidated story. It is also a useful case study in how a founder-led engineering firm professionalises — sponsors, subsidiaries, audited reporting and all — without losing the technical identity that won its first contracts in 1989. This article is educational content, not financial advice, and nothing in it is a recommendation to buy or sell any security.
Key takeaway: Avanceon is Pakistan's listed automation engineer: begun as a Lahore PLC-programming practice in 1989, incorporated in its present form in 2003 and listed in 2013, it designs, builds and maintains the control systems of factories across Pakistan and the Gulf — a project business steadied by recurring support work and a listed analytics subsidiary.